Contrary ResearchContrary Research
CompaniesReportsTopicsAbout
Subscribe
Report/
Contrary ResearchContrary Research

Powered by

Contrary

Discover

  • Companies
  • Reports
  • Topics
  • About

Connect

  • Email
  • LinkedIn
  • Twitter
Subscribe

Powered by

Contrary

© 2026 Contrary Research · All rights reserved

|Privacy Policy
Report/
Perspective
Venture & Startup Markets

Secondaries at a 61% Discount

July 1, 2023|2 min

A perspective from Contrary Research.

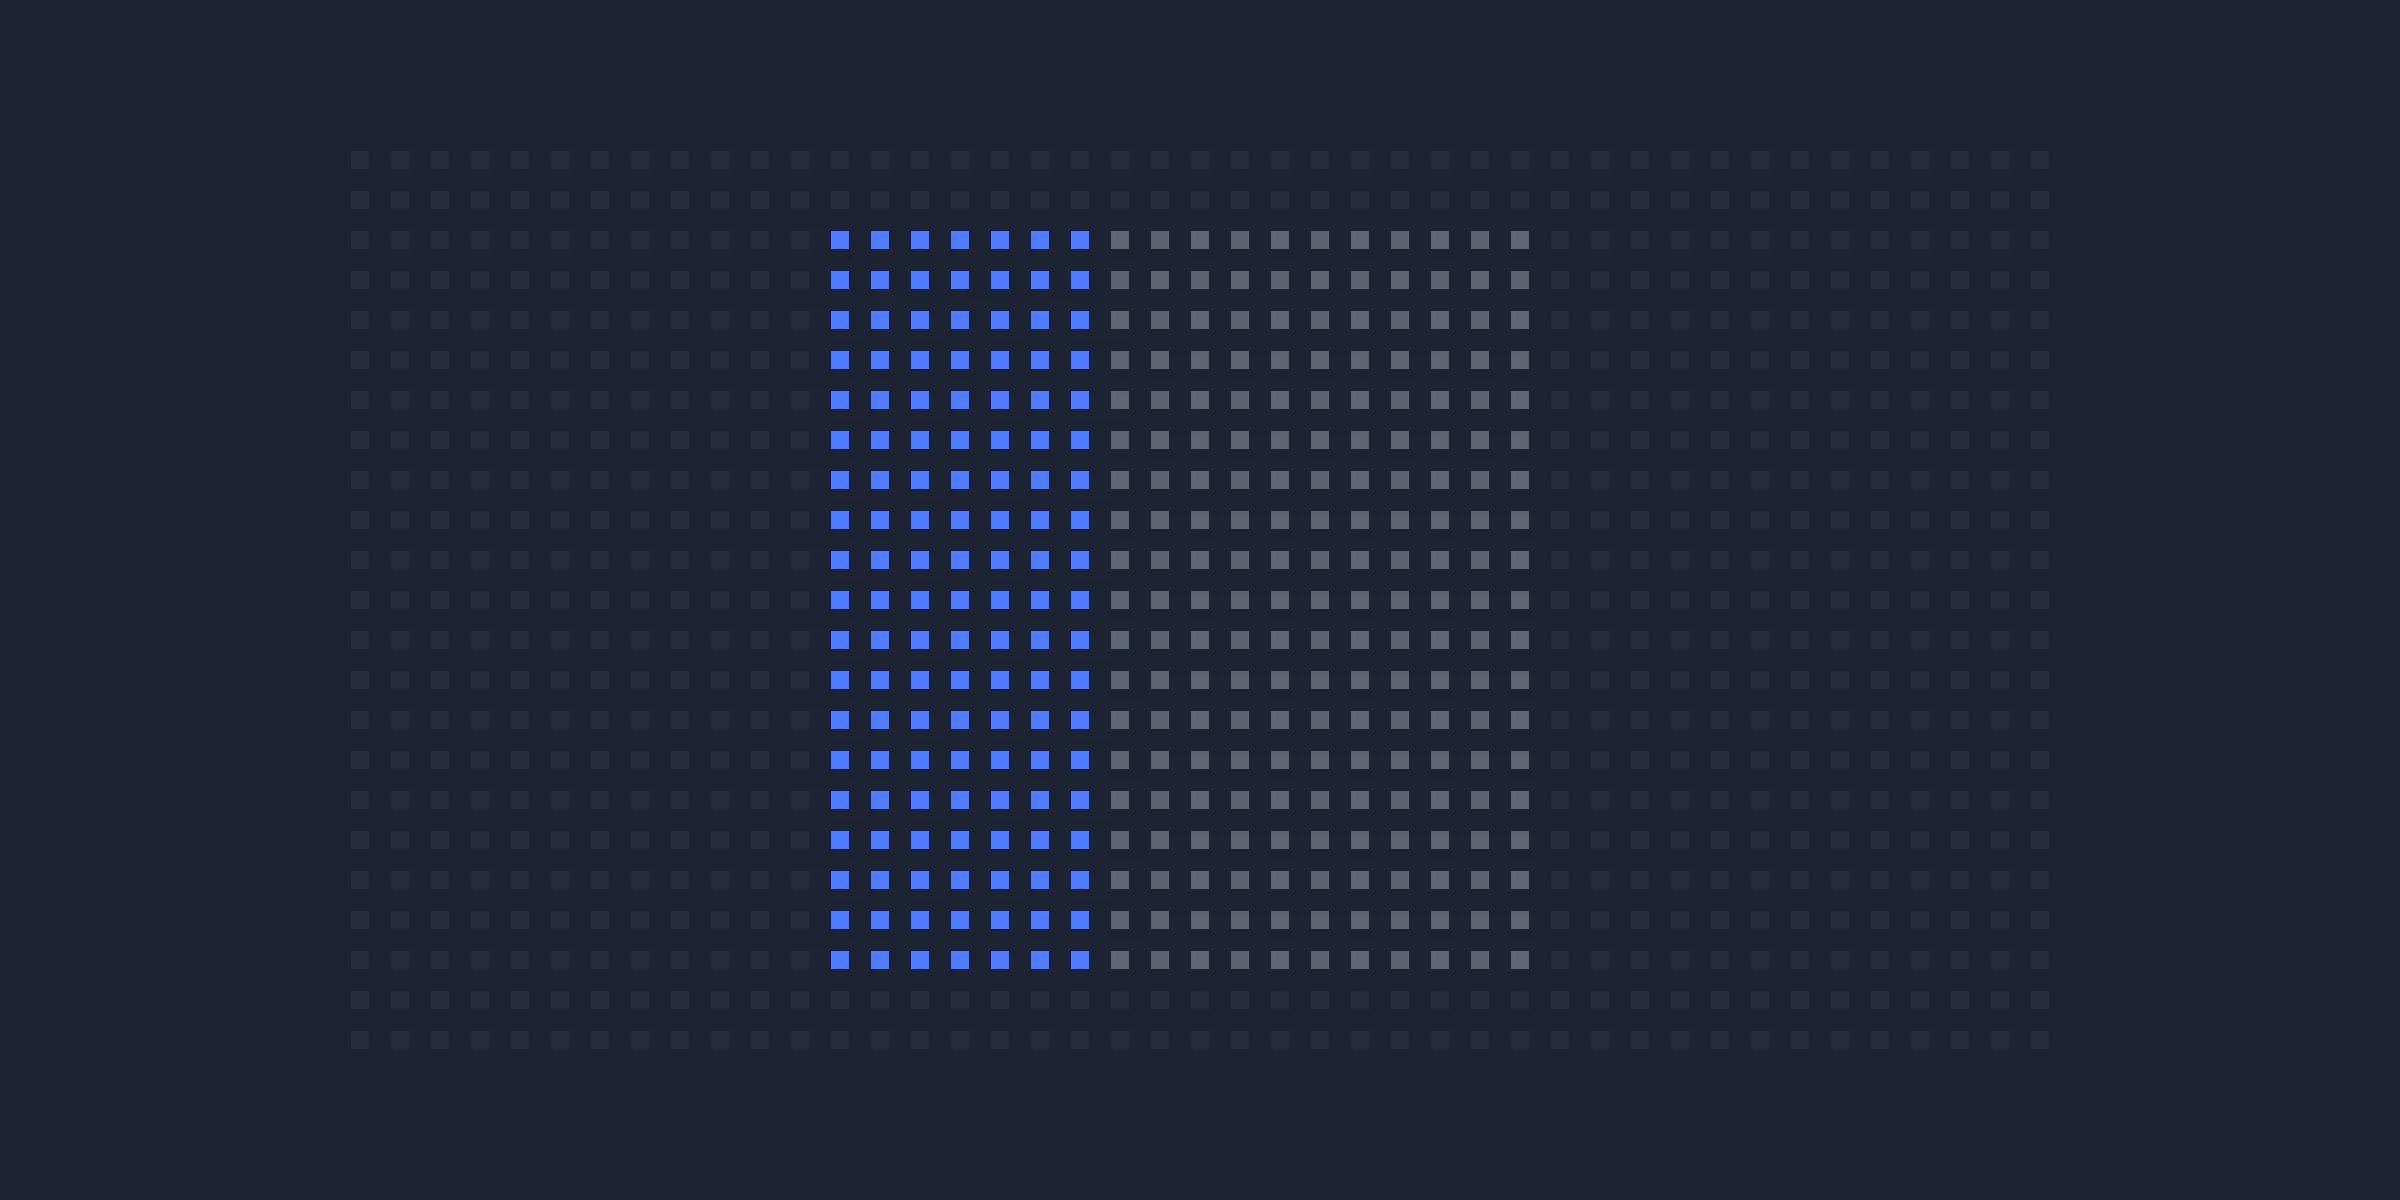
Dot-grid waffle chart: a blue block fills under two-fifths of a tall grey dot grid
  • Perspective
  • Authors1
  • Related Companies3

In the last 18 months, rising interest rates caused a downturn in the private market for startup funding. Investor confidence decreased and many highly-valued private companies saw a rapid decline in valuation. Meanwhile, VC funds and other asset managers are increasingly interested in secondary markets, where they can buy stakes in private companies at discounted prices. Back in 2021 and early 2022, many fund managers couldn't get the ownership they desired or even participate in highly sought-after startups’ primary rounds due to high demand and valuations at the time. Today, however, fewer initial rounds and IPOs combined with more down rounds and industry-wide devaluations have made secondary prices more appealing.

At the same time, founders, employees, and investors are facing increasing pressure to sell their shares, pushing down secondary prices further. As of May 31, 2023, startup stocks sold at a median 61% discount versus their last funding round valuations. Nearly 90% of the companies whose shares traded in May 2023 had not raised capital in at least a year, and a third hadn’t raised new funding in two years or more. Caplight's secondary exchange saw an increase in bids for secondary shares, resulting in a decreased spread between buyers and sellers.

In this challenging environment, startups may occasionally face the difficult reality of down rounds or even secondary transactions at discounted prices. However, it is important to remember that the best companies will be able to weather the storm and emerge stronger than ever. These setbacks are temporary hurdles, providing opportunities for introspection and strategic realignment. By embracing the challenges head-on, startups can refine their business models, optimize their operations, and demonstrate resilience to investors and stakeholders. In doing so, they can attract renewed interest and support, ultimately positioning themselves for long-term success.

Authors

  • Kyle Harrison

    General Partner @ Contrary

    See articles

Important Disclosures

This material has been distributed solely for informational and educational purposes only and is not a solicitation or an offer to buy any security or to participate in any trading strategy. All material presented is compiled from sources believed to be reliable, but accuracy, adequacy, or completeness cannot be guaranteed, and Contrary LLC (Contrary LLC, together with its affiliates, “Contrary”) makes no representation as to its accuracy, adequacy, or completeness.

The information herein is based on Contrary beliefs, as well as certain assumptions regarding future events based on information available to Contrary on a formal and informal basis as of the date of this publication. The material may include projections or other forward-looking statements regarding future events, targets or expectations. Past performance of a company is no guarantee of future results. There is no guarantee that any opinions, forecasts, projections, risk assumptions, or commentary discussed herein will be realized. Actual experience may not reflect all of these opinions, forecasts, projections, risk assumptions, or commentary.

Contrary shall have no responsibility for: (i) determining that any opinions, forecasts, projections, risk assumptions, or commentary discussed herein is suitable for any particular reader; (ii) monitoring whether any opinions, forecasts, projections, risk assumptions, or commentary discussed herein continues to be suitable for any reader; or (iii) tailoring any opinions, forecasts, projections, risk assumptions, or commentary discussed herein to any particular reader’s objectives, guidelines, or restrictions. Receipt of this material does not, by itself, imply that Contrary has an advisory agreement, oral or otherwise, with any reader.

Contrary is registered with the Securities and Exchange Commission as an investment adviser under the Investment Advisers Act of 1940. The registration of Contrary in no way implies a certain level of skill or expertise or that the SEC has endorsed Contrary. Investment decisions for Contrary clients are made by Contrary. Please note that, although Contrary manages assets on behalf of Contrary clients, Contrary clients may take any position (whether positive or negative) with respect to the company described in this material. The information provided in this material does not represent any investment strategy that Contrary manages on behalf of, or recommends to, its clients.

Different types of investments involve varying degrees of risk, and there can be no assurance that the future performance of any specific investment, investment strategy, company or product made reference to directly or indirectly in this material, will be profitable, equal any corresponding indicated performance level(s), or be suitable for your portfolio. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Investors should seek financial advice regarding the appropriateness of investing in any security of the company discussed in this presentation.

Please see www.contrary.com/legal for additional important information.

Authors

  • Kyle Harrison

    General Partner @ Contrary

    Kyle Harrison is a General Partner at Contrary where he’s invested in companies like Anduril, Ramp, Base Power, Valar Atomics, and Cursor, and is the Founder of Contrary Research. Over the past decade, Kyle has spent time as a partner at Index Ventures and Coatue investing in companies like Databricks, Snowflake, Plaid, Toast, and Persona.

    See articles

Related Companies

All companies
  • Equitybee logo
    Venture & Startup MarketsSeries B
    Venture & Startup MarketsSeries B

    Equitybee

    Equitybee is a platform that helps private company’s employees access the funding they need to exercise their stock options by connecting them with investors.

    1 PerspectiveMemo
  • Carta logo
    Venture & Startup MarketsSeries G
    Venture & Startup MarketsSeries G

    Carta

    Carta was built as a platform to manage a company’s cap table and has expanded to address the broader suite of needs in managing an organization’s financial and operational complexity.

    1 PerspectiveMemo
  • Pulley logo
    Venture & Startup MarketsSeries B
    Venture & Startup MarketsSeries B

    Pulley

    Pulley is an equity management solution that serves more than 5K companies as of August 2024, offering a comprehensive suite of products, including fundraising modeling, 409As and compliance, and equity issuance.

    1 PerspectiveMemo

Subscribe to the Research Rundown

Subscribe for a weekly digest on the best private technology companies.