Contrary ResearchContrary Research
CompaniesReportsTopicsAbout
Subscribe
Report/
Contrary ResearchContrary Research

Powered by

Contrary

Discover

  • Companies
  • Reports
  • Topics
  • About

Connect

  • Email
  • LinkedIn
  • Twitter
Subscribe

Powered by

Contrary

© 2026 Contrary Research · All rights reserved

|Privacy Policy
Report/
Deep Dive
Maritime & ShipbuildingAdvanced ManufacturingTech Policy & Geopolitics

Ships for America

June 29, 2026|3 min

In the 1980s, the US came to the conclusion that manufacturing and shipbuilding were commodity processes better suited for lower-cost labor markets in Asia. We’ve seen the same dynamic play out in semiconductors, batteries, mining, and pharmaceuticals. But shipbuilding represents a distinctly gnarly systems problem tangled between defense funding, policy, and a fading American manufacturing core.

  • Deep Dive
  • Authors2
  • Related Companies3

Most stories about American industrialism have turned from inspirational myths into cautionary tales. One such story is that of the New York Shipbuilding Corporation in Camden, New Jersey. Founded in 1899, New York Ship grew to become the largest shipyard in the world by 1917. World War I sparked such a shipbuilding boom that the War Department had to fund a new city — Yorkship Village — just to house the labor force for New York Ship; it was the first federally funded planned community.
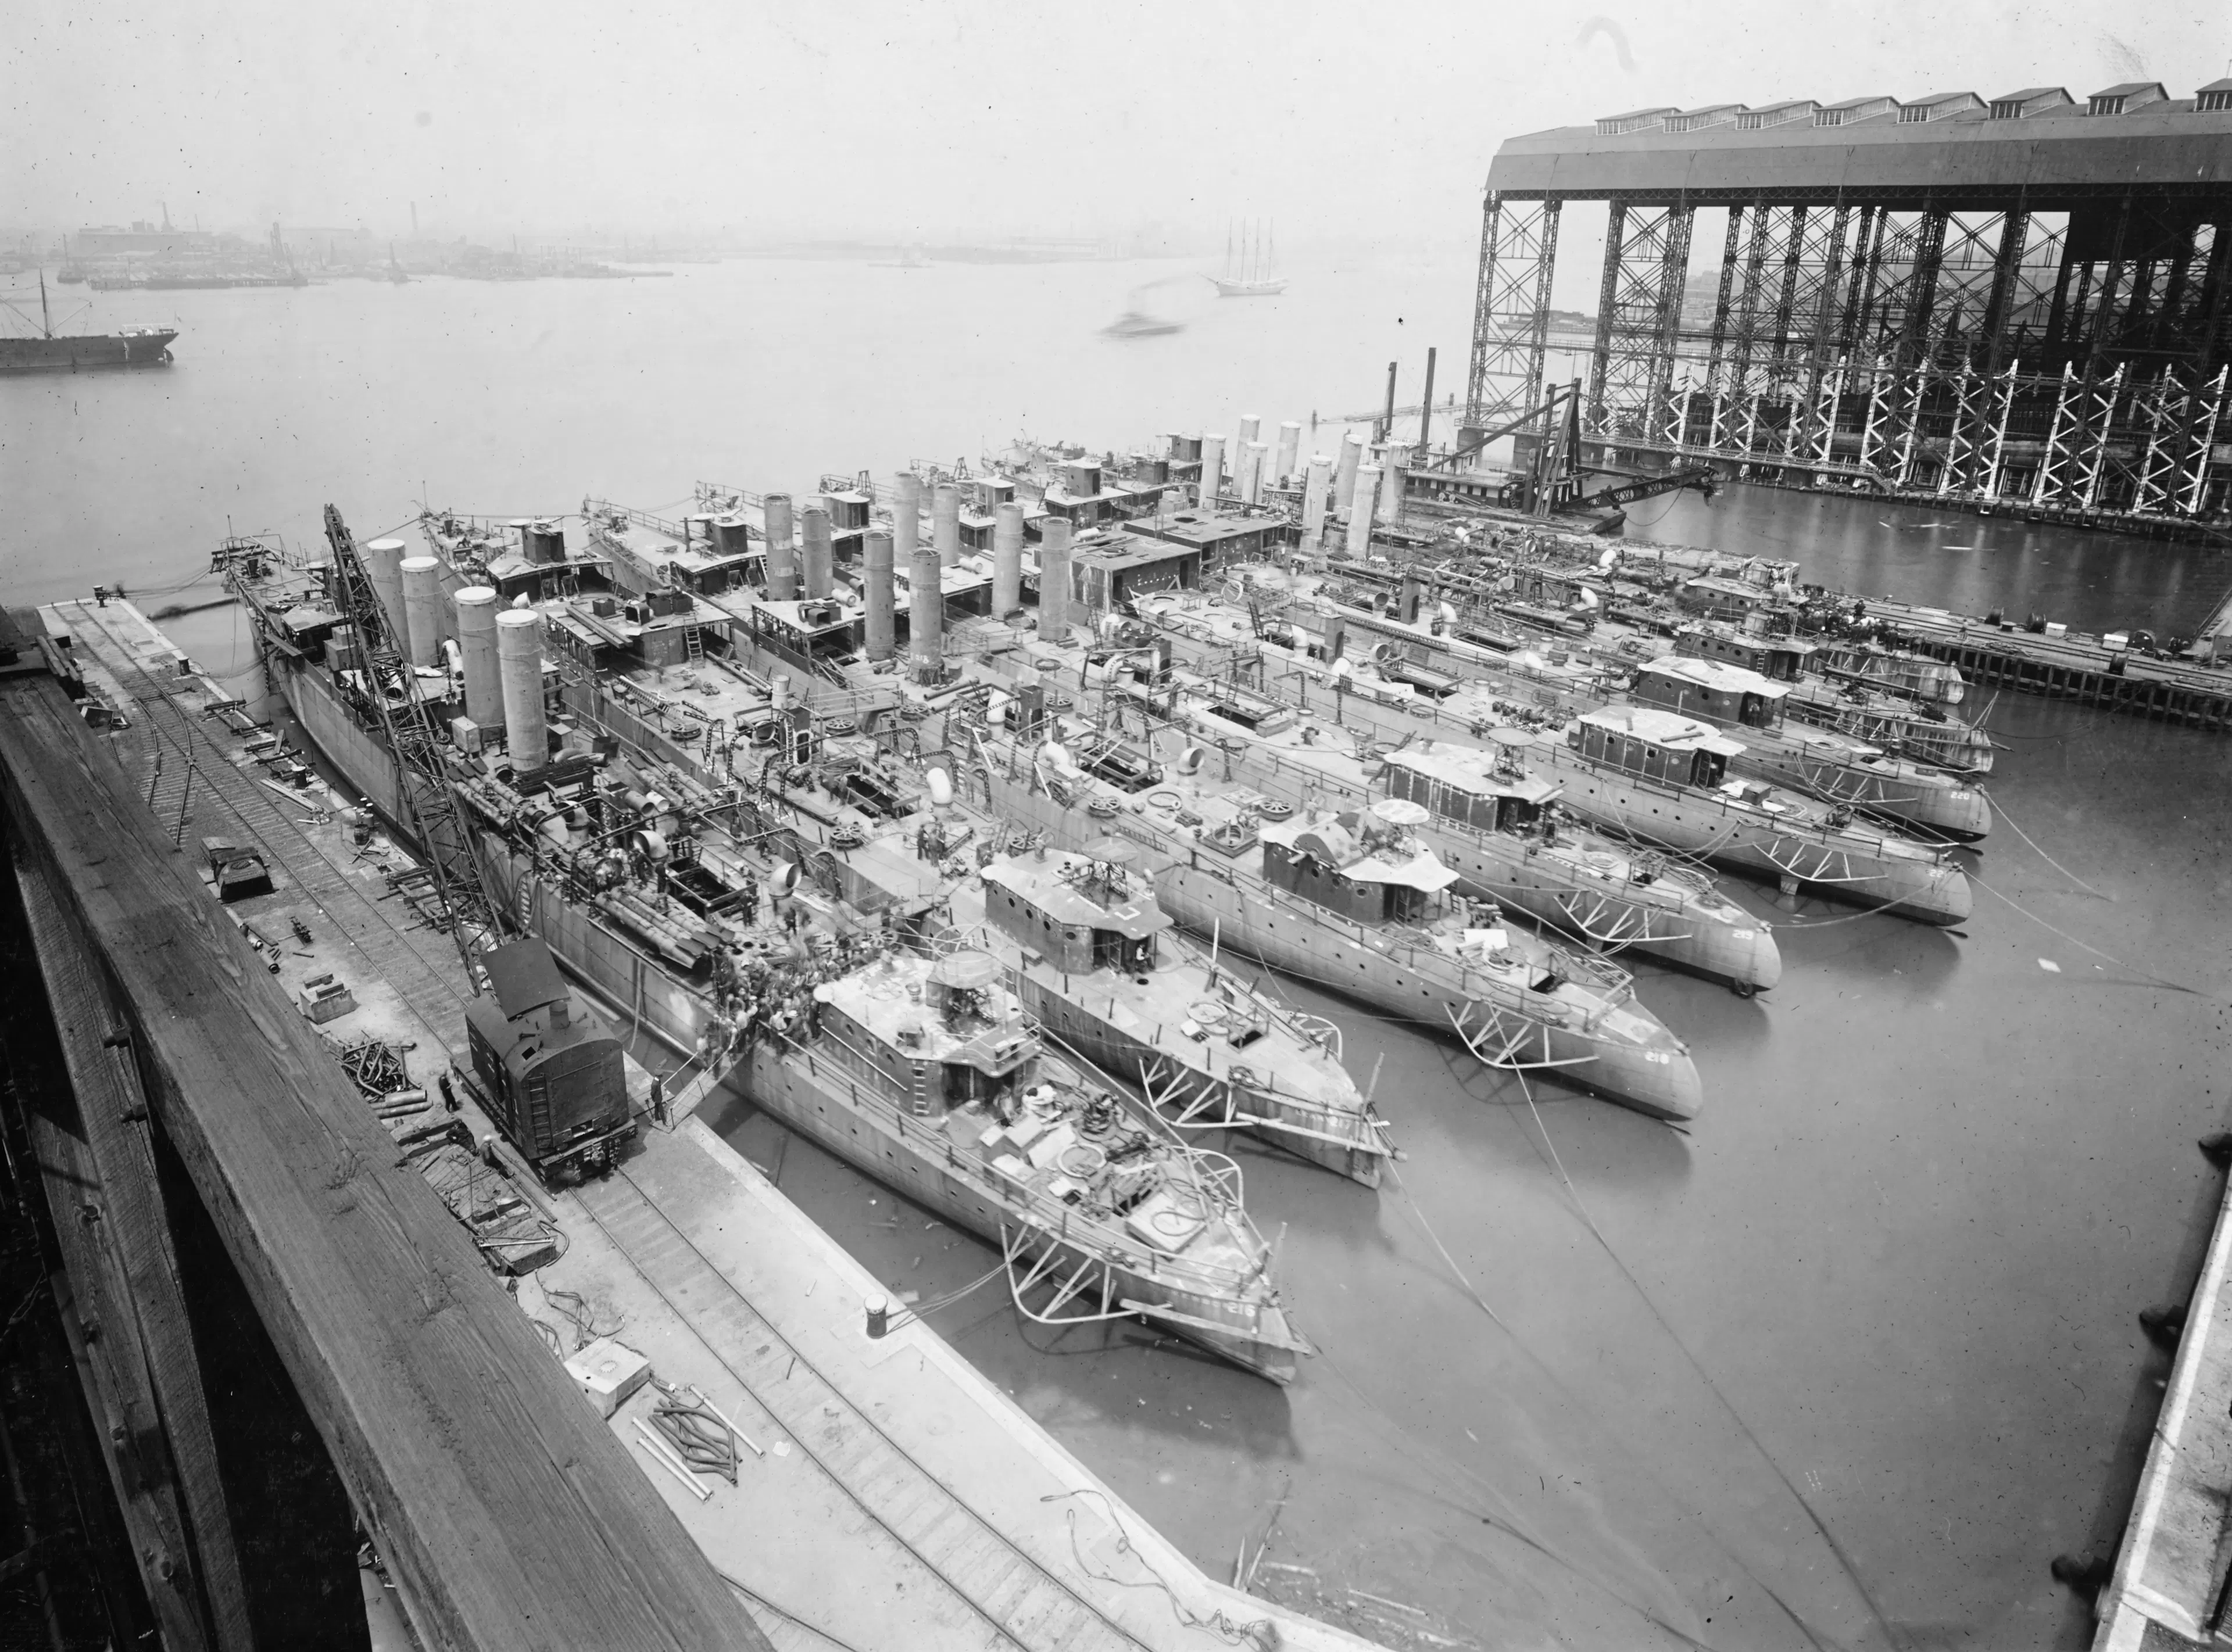
New York Shipbuilding Corporation shipyard in 1919

Source: Naval History and Heritage Command

This piece was originally published in Arena Magazine.

By the Second World War, New York Ship employed 47K across a 160-acre site along two miles of the Delaware River. What started as a factory had become an entire economy built to power the largest and most productive shipyard on Earth. New York Ship delivered 670 merchant and naval ships during its life, including three nuclear submarines and even the first nuclear-powered merchant ship.

By the end of WWII, America’s fleet represented 50 million deadweight tons — a measure of total carrying capacity — two-thirds of global tonnage. But after the war ended, the burden of upkeep for such a large fleet felt unnecessary, leading the US to immediately start mothballing and scrapping ships rather than maintaining them. The Cold War sustained demand for specialized naval work, like nuclear submarines and carriers, but that work concentrated in a select group of dedicated yards. Meanwhile, commercial shipbuilding migrated to lower-cost foreign yards. Caught between a shrinking commercial market and increasingly specialized naval contracts, New York Ship didn’t have the business to stay afloat. By 1968, it had shut its doors. Camden, the city that powered New York Ship, tracks an eerie road map for what happens when industrialism falters. The city lost a third of its population, including 30K manufacturing jobs. It now faces a poverty rate of 28.5% and has become one of the most dangerous cities in the country.

The New York Shipbuilding Corporation is just one of dozens of examples of the cost of assuming that America no longer needed a strong industrial base. Particularly in the 1980s, the US came to the conclusion that manufacturing and shipbuilding were commodity processes better suited for lower-cost labor markets in Asia. We’ve seen the same dynamic play out in semiconductors, batteries, mining, and pharmaceuticals. But shipbuilding represents a distinctly gnarly systems problem tangled between defense funding, policy, and a fading American manufacturing core.

This is an excerpt. The full piece is available in Arena Magazine.

Authors

  • Sawsan Haider

    Senior Fellow

    See articles
  • Kyle Harrison

    General Partner @ Contrary

    See articles

Important Disclosures

This material has been distributed solely for informational and educational purposes only and is not a solicitation or an offer to buy any security or to participate in any trading strategy. All material presented is compiled from sources believed to be reliable, but accuracy, adequacy, or completeness cannot be guaranteed, and Contrary LLC (Contrary LLC, together with its affiliates, “Contrary”) makes no representation as to its accuracy, adequacy, or completeness.

The information herein is based on Contrary beliefs, as well as certain assumptions regarding future events based on information available to Contrary on a formal and informal basis as of the date of this publication. The material may include projections or other forward-looking statements regarding future events, targets or expectations. Past performance of a company is no guarantee of future results. There is no guarantee that any opinions, forecasts, projections, risk assumptions, or commentary discussed herein will be realized. Actual experience may not reflect all of these opinions, forecasts, projections, risk assumptions, or commentary.

Contrary shall have no responsibility for: (i) determining that any opinions, forecasts, projections, risk assumptions, or commentary discussed herein is suitable for any particular reader; (ii) monitoring whether any opinions, forecasts, projections, risk assumptions, or commentary discussed herein continues to be suitable for any reader; or (iii) tailoring any opinions, forecasts, projections, risk assumptions, or commentary discussed herein to any particular reader’s objectives, guidelines, or restrictions. Receipt of this material does not, by itself, imply that Contrary has an advisory agreement, oral or otherwise, with any reader.

Contrary is registered with the Securities and Exchange Commission as an investment adviser under the Investment Advisers Act of 1940. The registration of Contrary in no way implies a certain level of skill or expertise or that the SEC has endorsed Contrary. Investment decisions for Contrary clients are made by Contrary. Please note that, although Contrary manages assets on behalf of Contrary clients, Contrary clients may take any position (whether positive or negative) with respect to the company described in this material. The information provided in this material does not represent any investment strategy that Contrary manages on behalf of, or recommends to, its clients.

Different types of investments involve varying degrees of risk, and there can be no assurance that the future performance of any specific investment, investment strategy, company or product made reference to directly or indirectly in this material, will be profitable, equal any corresponding indicated performance level(s), or be suitable for your portfolio. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Investors should seek financial advice regarding the appropriateness of investing in any security of the company discussed in this presentation.

Please see www.contrary.com/legal for additional important information.

Authors

  • Sawsan Haider

    Senior Fellow

    Senior Fellow @ Contrary. In addition to her work at Contrary, Sawsan is currently pursuing an MS in Bioethics at Harvard Medical School. She has previously conducted AI alignment research at the University of Cambridge and was an analyst at Spring Venture Services.

    See articles
  • Kyle Harrison

    General Partner @ Contrary

    Kyle Harrison is a General Partner at Contrary where he’s invested in companies like Anduril, Ramp, Base Power, Valar Atomics, and Cursor, and is the Founder of Contrary Research. Over the past decade, Kyle has spent time as a partner at Index Ventures and Coatue investing in companies like Databricks, Snowflake, Plaid, Toast, and Persona.

    See articles

Related Companies

All companies
  • Hadrian logo
    Advanced ManufacturingSeries C
    Advanced ManufacturingSeries C

    Hadrian

    Hadrian is a manufacturing company that has built vertically integrated technology for high-precision manufacturing, with modules including quoting, programming, machining, and inspection.

    15 ReportsMemo
  • Saronic logo
    Defense SystemsSeries C
    Defense SystemsSeries C

    Saronic

    Saronic builds autonomous surface vessels (ASVs) for the US Navy and other defense customers, with a focus on speed, modularity, and operational autonomy.

    8 ReportsMemo
  • Navier logo
    Maritime & ShipbuildingSeed
    Maritime & ShipbuildingSeed

    Navier

    Navier aims to become the maritime company of the future. It builds electric passenger hydrofoils.

    2 ReportsMemo

Subscribe to the Research Rundown

Subscribe for a weekly digest on the best private technology companies.